Can I deduct all payments made to her student loan on her federal taxes?
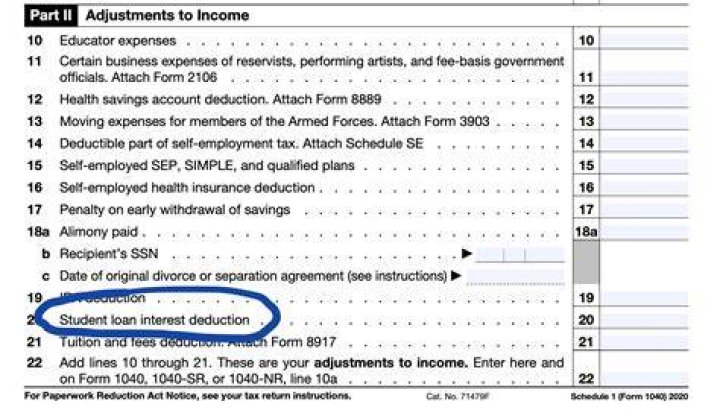
The student loan interest deduction is a federal income tax deduction that allows you to subtract up to $2,500 of the interest you paid on qualified student loans from your taxable income. 1 It is one of several tax breaks available to students and their parents to help pay for higher education.
Can you write off student loan payments?
In many cases, the interest portion of your student loan payments paid during the tax year is tax-deductible. Your tax deduction is limited to interest up to $2,500 or the amount of interest you actually paid, whichever amount is less.
Can a mortgage refinance be used to pay off student loans?
According to experts, there’s a lot to think about here. A mortgage refinance can certainly be used to pay off your student loans. To do it, you’d need a cash-out refinance, which means taking out a new mortgage loan that’s higher than your current loan’s balance.
How does the student loan interest deduction work?
Overview of the Student Loan Interest Deduction: The Student Loan Interest Deduction allows an individual to deduct any interest actually paid, not just accumulated, on a student loan during the calendar year, as long as certain conditions are met.
How are student loan repayments calculated on tax return?
If the employee had to make student loan repayments during the tax year 2018 to 2019, their payroll record will state whether their repayments are made on plan 1 or plan 2. Student loan deductions are not calculated on a cumulative basis]
How much student loan income is tax free?
Section 2206 of the CARES Act allows a portion of student loan payments to be excluded from income. Whether those payments are made directly to the employee or the lender, they will be tax-free. The income exclusion is up to $5,250 per year per employee.
